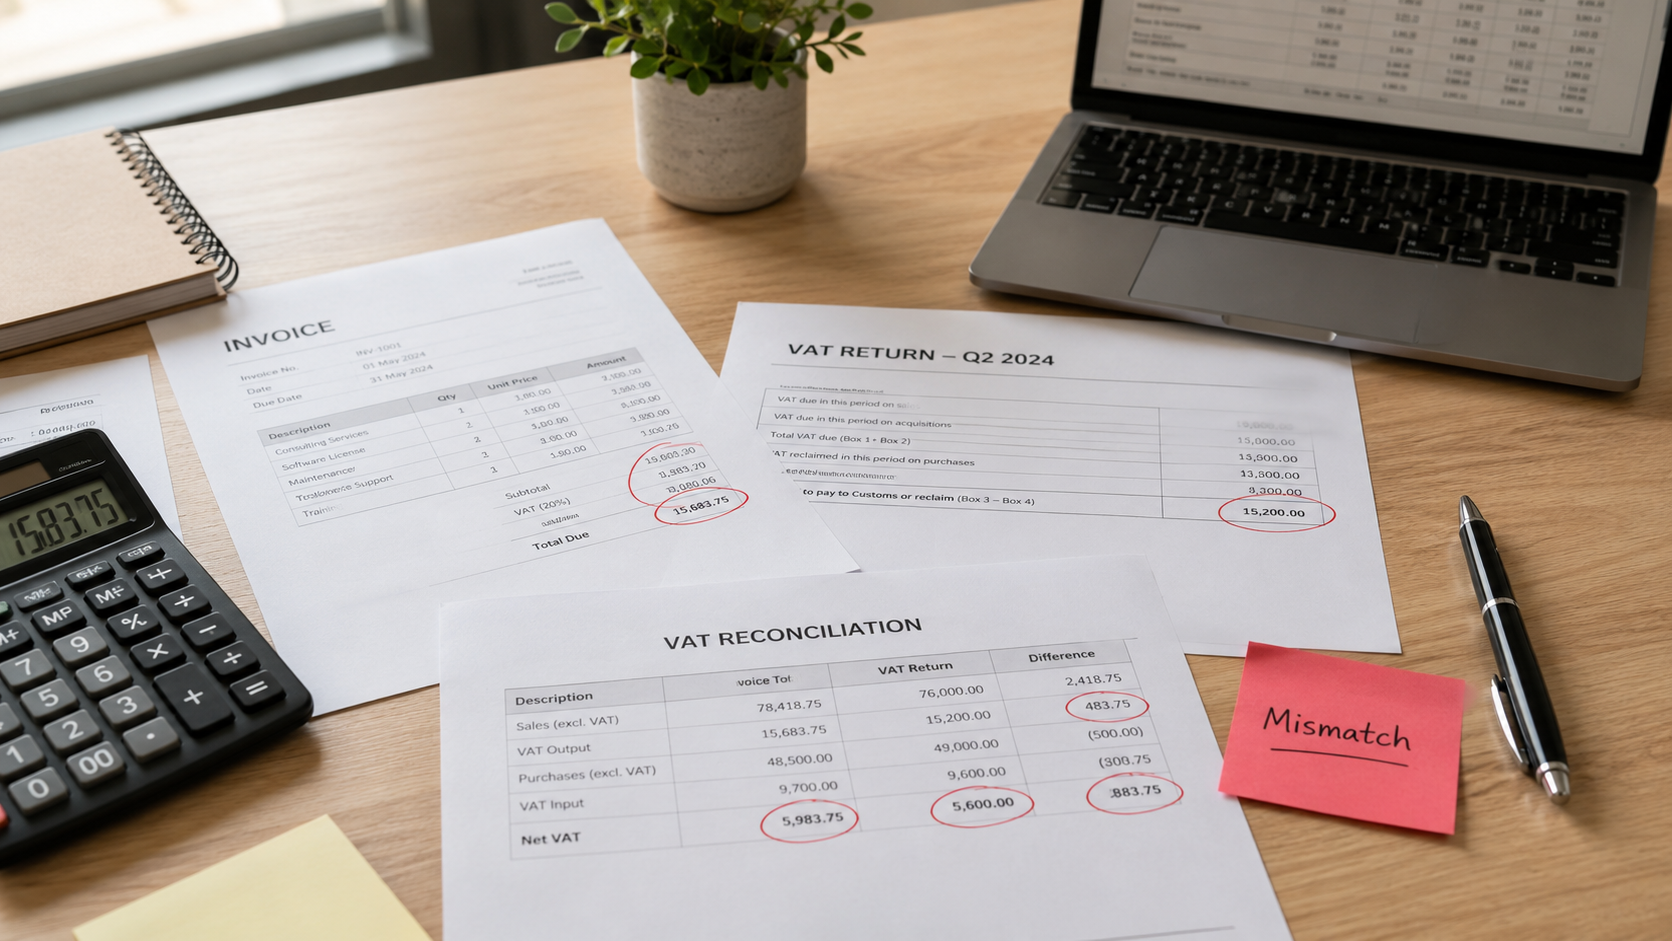
A VAT reconciliation difference is not proof of fraud. It is, however, evidence that the transaction story is incomplete. When the same differences recur, remain unexplained or concentrate around particular people and suppliers, they become signals management should investigate.
VAT records sit at the intersection of sales, procurement, inventory, payments and financial reporting. A weakness visible in the return may therefore point to a broader control failure: an unauthorized purchase, a fictitious supplier, an unrecorded sale, manipulated timing or a manual adjustment without support.
Why reconciliation gaps matter
A reconciliation compares records that should describe the same economic activity. Sales in the ledger should connect to VAT records and invoices. Purchases and input claims should connect to supplier documents, receipt of goods or services, payment and business use. Inventory movement should support quantities bought, transferred and sold.
Differences can arise for legitimate reasons, including timing, classification, returns, advances and corrections. Risk increases when those differences are not identified promptly, cannot be supported or are cleared through entries that bypass normal review.
The risk signal is rarely the difference alone. It is the absence of a clear explanation, a responsible owner and evidence of resolution.
That makes reconciliation a management control, not simply a compliance schedule. It provides a structured way to identify unusual activity before it becomes a regulatory, financial or reputational problem.
Patterns that deserve closer review
One exception may be an error. A pattern can indicate process abuse or deliberate concealment. Teams should look beyond total values and consider who initiated the transaction, how it was approved and what evidence exists.
Input claims repeatedly lack matching receipt, inventory or payment evidence.
Manual VAT adjustments rise near reporting deadlines or reverse in the next period.
Credit notes cluster around particular customers, users, branches or approval routes.
Supplier names, registration details or bank accounts change without independent validation.
Sales, stock and VAT records show unexplained quantity or timing differences.
Old reconciling items are repeatedly carried forward or cleared in round amounts.
These signals should trigger proportionate review, not immediate accusation. The purpose is to establish facts, preserve evidence and understand whether the issue is isolated, systemic or intentional.
Separate error, control failure and misconduct
Effective investigation begins by distinguishing three possible causes. A processing error may require correction and training. A control-design failure may require changed roles, system rules or review thresholds. Potential misconduct requires controlled escalation, evidence preservation and independent assessment.
Error
An isolated mistake with a credible transaction trail, no pattern of benefit and prompt, transparent correction.
Control failure
A recurring gap caused by unclear ownership, incompatible systems, weak review or a process that staff regularly bypass.
Fraud indicator
An unusual pattern involving concealment, personal benefit, fabricated evidence, overridden controls or resistance to review.
Investigation principle
Protect the evidence before correcting the entry.
Where deliberate manipulation may be involved, retain original records, access logs, approvals and communications before changes are made to systems or documents.
Management should involve the right functions early. Tax and finance can quantify the difference; procurement and operations can establish transaction reality; internal audit, legal or an independent adviser may be needed where integrity concerns arise.
A practical VAT reconciliation control
A strong control connects data, review and action. It should be performed frequently enough to identify issues before filing and designed so material exceptions cannot disappear inside a net total.
- Use controlled source data: extract ledger, VAT, sales, purchase and inventory records from named systems with a documented cut-off.
- Reconcile both value and volume: totals may agree while transaction quantities, counterparties or timing remain inconsistent.
- Define exception thresholds: include value, age, frequency, manual intervention and unusual-party criteria.
- Assign independent review: the preparer should not approve their own reconciling entries or close unexplained items.
- Track resolution: record the cause, owner, financial effect, corrective action, due date and evidence of closure.
- Escalate patterns: recurring exceptions should move from transaction correction to root-cause and fraud-risk review.
Technology can help compare large datasets and identify unusual relationships, but it does not replace judgment. The reviewer must understand the business process well enough to recognize when a technically valid entry lacks commercial logic.
A focused agenda for the first 90 days
Organizations can strengthen visibility quickly by focusing first on high-volume and high-risk transaction streams.
- Map the reconciliation universe.List the ledgers, VAT records, inventory reports and supporting documents that should agree.
- Age existing differences.Separate current timing items from old, repeated or unsupported balances requiring escalation.
- Analyze patterns.Group exceptions by user, supplier, customer, branch, period, entry type and approval path.
- Strengthen review rights.Restrict manual adjustments, separate preparation from approval and retain system evidence.
- Report root causes.Give management a concise view of exposure, recurring causes, owners, due dates and unresolved fraud indicators.
The objective is not to treat every reconciliation gap as wrongdoing. It is to ensure that anomalies receive enough attention to determine what they mean.
When VAT reconciliation becomes part of the fraud-risk framework, management gains more than compliance confidence. It gains an early-warning view across procurement, inventory, revenue, cash and reporting—the processes where financial integrity is established or lost.