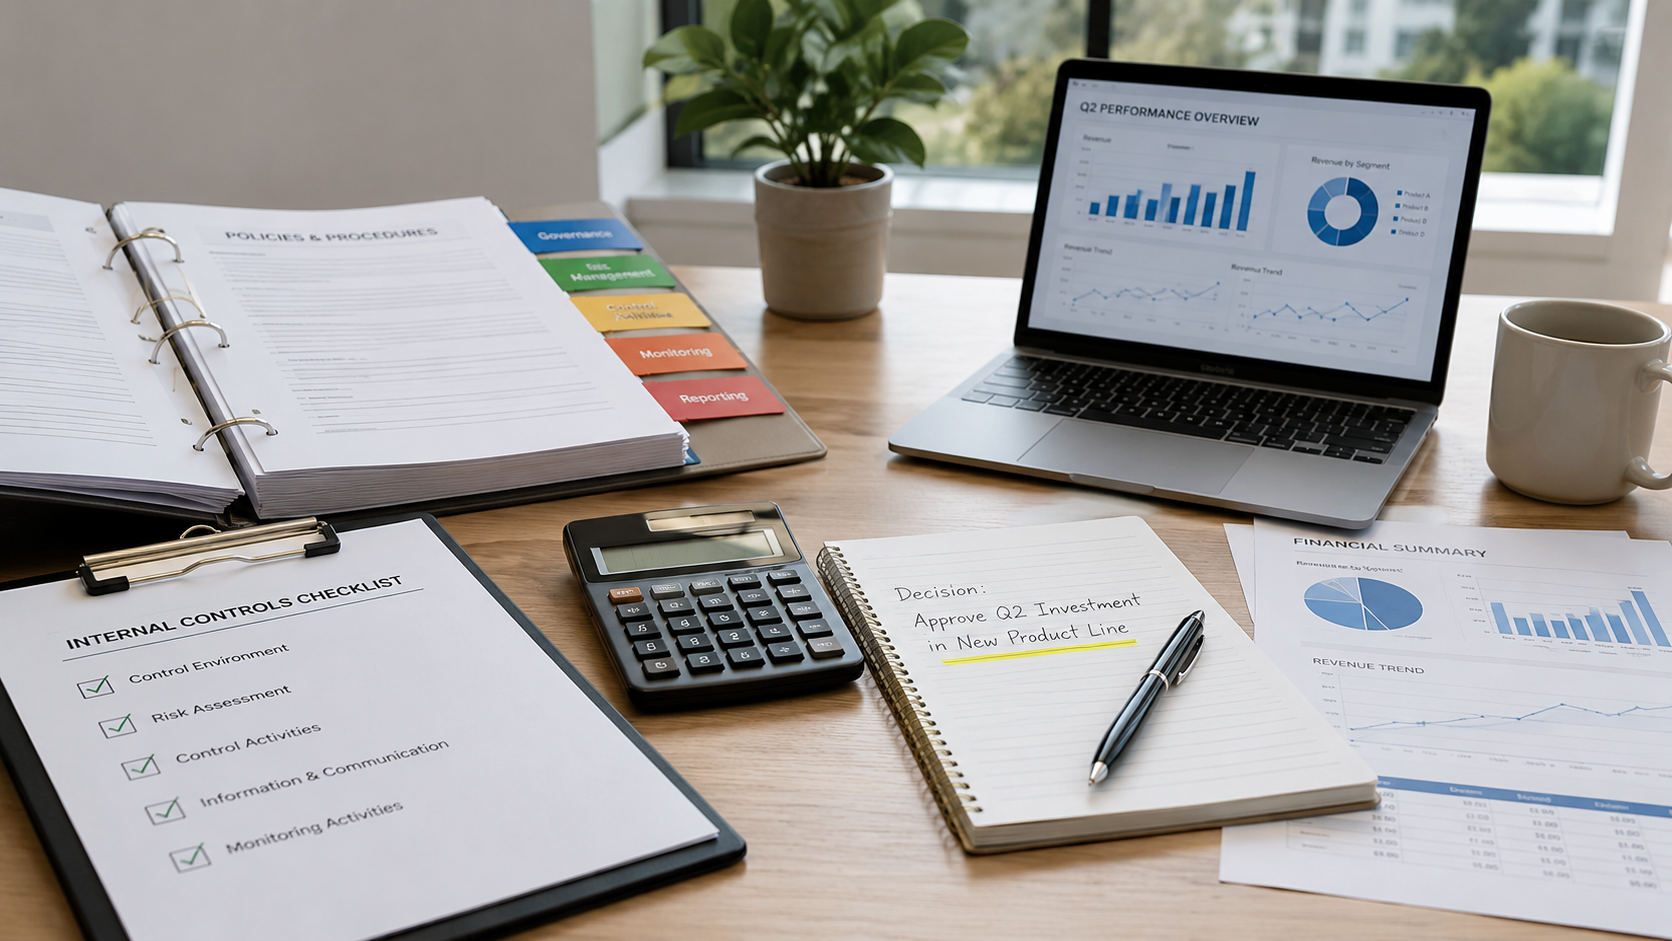
Controls are often described as safeguards: mechanisms that prevent error, misuse and non-compliance. That is only half their value. When they are designed around real decisions, controls also improve the information leaders receive and the confidence with which they can act.
A growing organization makes more decisions through more people, locations and systems. Informal supervision becomes less effective, while the cost of unclear authority and unreliable data increases. Strong controls create a shared operating discipline that allows decisions to move faster without losing accountability.
The myth that control slows business down
Poorly designed controls can create delay. Repeated approvals, unclear limits and forms that serve no decision may add work without reducing risk. But this is not an argument against control; it is an argument for better design.
A useful control answers a clear question. Is this commitment within budget? Has the customer met the agreed credit conditions? Does the reported margin reflect all costs? Is the person approving the transaction appropriately independent? When these questions are answered at the right point, teams spend less time correcting problems later.
Good controls do not replace judgment. They give judgment reliable evidence, a clear owner and an agreed boundary.
How controls improve decision quality
Decision quality depends on more than analysis. It depends on the completeness of the underlying information, clarity over who can decide, and visibility of what happened after approval.
Reliable inputs
Reconciliations, validation and review help leaders distinguish confirmed facts from estimates, assumptions and unresolved differences.
Clear authority
Delegated limits put routine decisions close to the work while reserving material or unusual matters for the right level.
Visible exceptions
Exception reporting focuses management attention on transactions and outcomes outside agreed thresholds.
Closed feedback
Post-decision monitoring shows whether the expected result occurred and whether the control needs adjustment.
This creates a practical loop: evidence informs the decision, authority makes ownership clear, monitoring compares outcomes with expectations, and lessons improve the next decision.
Design principle
Put control where the decision happens.
A preventive check inside the normal workflow is usually stronger and faster than a retrospective review performed after the commitment is already made.
Warning signs that controls no longer fit
Control frameworks rarely fail at once. More often, the business changes while the framework stays still. A pattern of recurring exceptions signals that the operating model and its controls have drifted apart.
Teams rely on private spreadsheets because core reports are late or not trusted.
Approval requests repeatedly escalate because limits no longer reflect transaction values.
The same exceptions recur without a named owner, deadline or verified closure.
Managers spend meetings debating whose number is correct instead of deciding what to do.
Access rights and responsibilities still reflect former roles or organizational structures.
Controls are documented, but staff cannot explain why they matter or what evidence is required.
These issues affect more than compliance. They slow the organization, weaken accountability and increase the chance that leaders act on incomplete or inconsistent information.
A practical model for stronger controls
Strengthening control should begin with the decisions and risks that matter most—not with a long catalogue of procedures. Management can focus on four connected elements.
- Decision rights: define who recommends, reviews, approves and monitors each material decision.
- Minimum evidence: agree what information must exist before approval and where it will be retained.
- Exception thresholds: determine which deviations require escalation and how quickly they must be resolved.
- Management information: report a small set of reliable measures linked to action, not a large set of unowned metrics.
- Independent challenge: use finance, risk, internal audit or another reviewer to test whether controls operate as intended.
The framework should remain proportionate. A routine, low-value purchase should not follow the same path as a strategic investment. The control effort should rise with value, complexity, irreversibility and risk.
A focused agenda for the first 90 days
A short improvement cycle can remove friction and strengthen the information used by management without waiting for a full transformation programme.
- Identify ten critical decisions.Select the commitments and judgments with the greatest financial, operational, regulatory or reputational effect.
- Trace each decision end to end.Map the information, authority, system steps, evidence and monitoring from initiation through outcome.
- Remove duplicate and low-value checks.Simplify controls that repeat work without changing the decision or reducing a defined risk.
- Resolve the oldest exceptions.Assign owners and deadlines, address root causes and require evidence before an issue is closed.
- Build a decision-focused dashboard.Show material exceptions, forward-looking indicators and agreed actions alongside historical performance.
The objective is a control environment that people can understand and use. When controls reflect the way work actually happens, they create consistency without unnecessary bureaucracy.
Stronger controls ultimately give leaders a clearer view of choices and consequences. That clarity supports faster escalation, better allocation of resources and decisions the organization can execute with confidence.